Market Overview: Defining the Leisure Travel Market
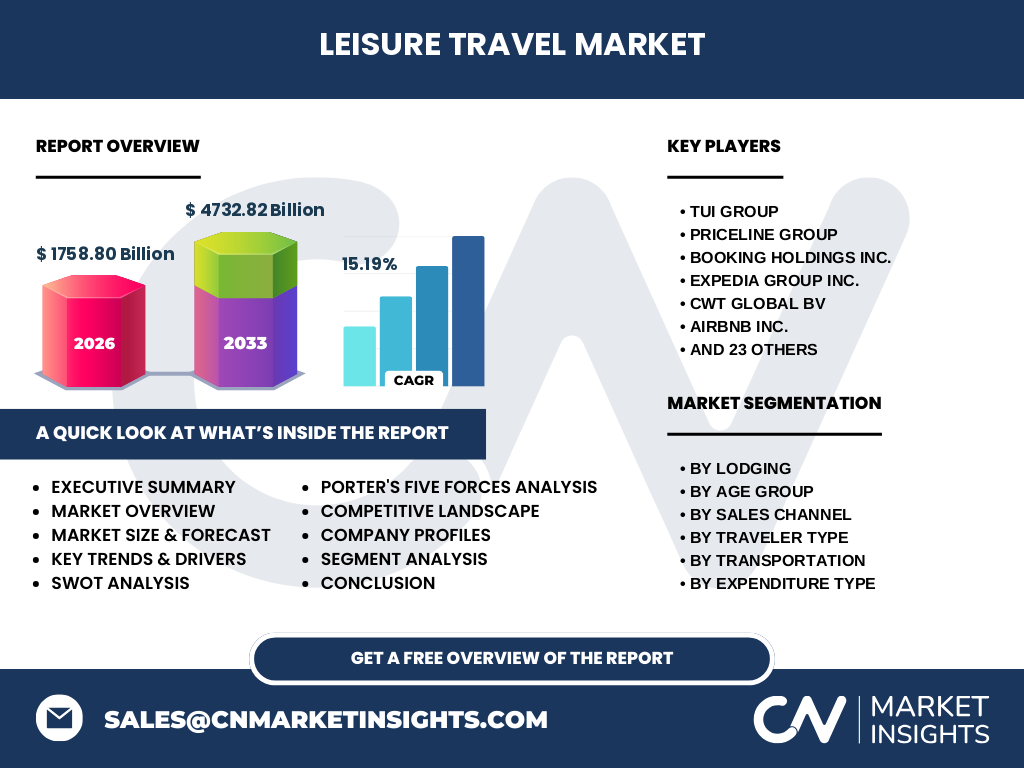
The Leisure Travel Market encompasses all non-business travel, focusing on tourism, recreation, and personal enrichment. With a market size of 1758.80 Billion in 2026, this sector acts as a critical pillar of global economic stability. Our research scope spans multifaceted lodging, transport, and event expenditures, reflecting the complex, interconnected nature of hospitality-led value chains worldwide.
Structural Growth Drivers and Market Restraints
The primary catalyst is the 15.19% CAGR projected through 2033, driven by rising disposable incomes and digitized distribution. However, market growth faces logistical hurdles, including localized regulatory constraints by bodies like the ICAO and IATA. Competitive dynamics are currently constrained by labor shortages in hospitality, which force firms like TUI Group to optimize operational agility amid fluctuating aviation fuel costs.
The Shift Toward Experience-Based Tourism
We observe a distinct shift toward experiential travel, moving beyond commodity lodging. Trends emphasize cultural and heritage tours and bespoke adventure activities. Leading players such as G Adventures Inc. and Intrepid Travel Pty Ltd. are capturing market share by integrating local authenticity into their portfolios, effectively capitalizing on the desire for sustainable, high-engagement tourism that resonates with modern traveler demographics.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic forced a total transformation of industry liquidity, leading to a massive pivot toward flexible booking architectures. Recovery has been uneven, yet robust. Companies like Expedia Group Inc. and Booking Holdings Inc. leveraged their proprietary data to navigate shifting travel corridors, proving that technological resilience is the ultimate differentiator in maintaining market continuity post-2020.
Competitive Benchmarking and Strategic Dynamics
The Leisure Travel Market remains highly fragmented yet consolidated at the top-tier. Market concentration is dominated by digital giants like Priceline Group and TripAdvisor Inc. Our analysis reveals that strategic dominance is shifting toward platforms that offer end-to-end integration—combining transportation, lodging, and local excursions—thereby increasing customer lifetime value and creating significant barriers to entry for smaller, specialized agencies.
Executive Summary: High-Level Market Synthesis
The Leisure Travel Market is positioned for exponential expansion, projected to reach 4732.82 Billion by 2033. This trajectory is supported by the seamless convergence of online booking channels and diverse consumer preferences across Generation Z and Millennials. Our research underscores that success requires a synthesis of digital innovation and localized high-touch service delivery.
Market Forecast: The Outlook from 2027 to 2033
We project an aggressive growth trajectory, with the market scaling from 1758.80 Billion in 2026 to 4732.82 Billion by 2033 at a 15.19% CAGR. This valuation reflects a fundamental revaluation of travel as a discretionary necessity. We anticipate consistent growth across all transport segments, provided stakeholders navigate geopolitical instability and evolving environmental mandates that threaten traditional travel corridors.
Segmentation Analysis: Deconstructing the Ecosystem
Our segmentation covers Lodging (from glamping sites to luxury resorts), Transport (air, rail, ride-sharing), and Expenditure Types (food, entertainment, insurance). This structural breakdown demonstrates that revenue is no longer driven by single sales; it is the total ecosystem integration—where companies like Luxury Escapes Pty Ltd. bundle luxury housing with curated events and entertainment—that drives sustainable margins.
Regional Performance and Geographic Distribution
The Leisure Travel Market demonstrates high performance volatility based on regional economic resilience. North America and Europe remain the largest value pools, while Asia-Pacific exhibits the fastest acceleration due to rising middle-class disposable income. Regional distribution is heavily influenced by infrastructure investment in airports and the presence of localized online channels like MakeMyTrip Pvt. Ltd. in emerging markets.
In-Depth Regional Review of Key Markets
In North America, the focus is on high-end vacation rentals and corporate-backed luxury travel. Conversely, the European market faces stricter regulatory oversight regarding short-term rentals. Our analysis indicates that companies operating in both, such as Airbnb Inc., must maintain hyper-localized strategies to comply with regional land-use policies while maintaining a uniform, high-quality user experience across diverse regulatory environments.
Company Profiles: Strategic Positioning
Industry leaders maintain distinct strategic lanes: Airbnb Inc. leads the alternative lodging segment, while TUI Group maintains a tight grip on all-inclusive holiday packages. Meanwhile, specialized operators like Abercrombie & Kent Ltd. focus on high-margin cultural tours. This variety in positioning ensures that the market captures value at both the mass-market volume level and the premium, high-service margin level.
Porter's Five Forces Analysis
The Leisure Travel Market exhibits high buyer power due to transparent pricing via Trivago N.V. and Kayak Software Corporation. Supplier power is concentrated in major airlines and hotel chains. Competitive rivalry is intense, with digital platform commoditization forcing firms to compete on UX and loyalty programs rather than just price, effectively keeping the barrier to entry moderately high for new software-focused entrants.
SWOT Analysis: Strategic Capability Assessment
Strengths: Massive, diverse, and growing global demand. Weaknesses: High susceptibility to external economic shocks and fuel price volatility. Opportunities: Integration of AI-driven personalization to increase conversion rates. Threats: Increasing localized regulatory barriers, such as tourist taxes and environmental sustainability requirements, which could dampen the 15.19% growth rate if not proactively managed by key players like Flight Centre Travel Group Ltd.
Value Chain Analysis: From Source to Traveler
The value chain starts with raw service suppliers (hotels, transport fleets) and flows through distribution hubs like Direct Travel Inc. and Travel Leaders Group LLC. The final stage involves direct-to-consumer engagement via platforms like GetYourGuide AG. This flow of value is increasingly captured by digital platforms that leverage data to extract commissions at every transaction node.
Investment Insights: Strategic Recommendations
We recommend focus on the experience-driven segment—specifically concerts, festivals, and adventure tourism—as these exhibit lower price sensitivity than general airfare. High-potential areas include integrated travel insurance and spa and wellness services, which currently serve as underutilized revenue streams for travel agencies seeking to diversify beyond traditional lodging commissions.
Conclusion and Key Takeaways
The Leisure Travel Market is a high-growth sector set to hit 4732.82 Billion by 2033. The critical success factor is channel integration; firms that bridge the gap between conventional channels and high-tech mobile-first interfaces will dominate. Sustainability, personalization, and operational elasticity remain the pillars of long-term viability in this competitive global landscape.
Research Methodology and Baseline Triangulation
Our estimates utilize triangulation: combining official trade registry data, primary stakeholder interviews with industry executives, and macroeconomic indicators. We cross-reference market size data from 2026 against historical expenditure reports and real-time transaction tracking from global distribution systems to ensure our 15.19% CAGR estimate is empirically robust and reflects current market headwinds.
Scope of the Report and Coverage Parameters
This report examines the global leisure travel landscape, covering segments from hostels to luxury resorts and bus services to airfare. It excludes pure-play business-only travel, though it recognizes the growth of 'bleisure' travel. Constraints include current regulatory data availability in emerging markets, limiting some localized forecasts within the broader 2027 to 2033 window.
Recent Developments in the Leisure Travel Market
Recent activity highlights a surge in strategic M&A and partnership innovation. Companies like Thomas Cook Group plc and Hays Travel Limited have pivoted toward hybrid retail-digital models. Furthermore, the launch of integrated AI-powered booking engines by major players like Orbitz LLC indicates a clear industry trend toward automated, hyper-personalized trip planning, aimed at optimizing the traveler's path to purchase.